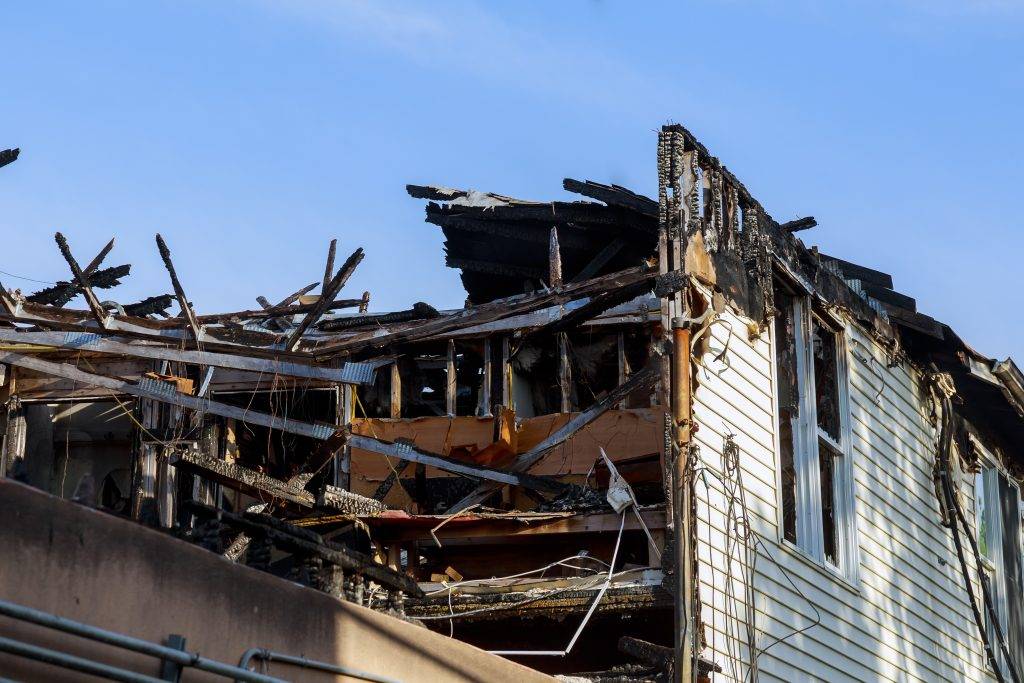
Fire Damage Adjuster in Furlong, PA
A fire in your home or business changes everything overnight. In the days that follow, you’re likely juggling insurance paperwork, contractor estimates, and decisions about temporary housing — all while trying to process what’s been lost. At Alliance Adjustment Group, we work alongside Furlong property owners to organize that process and make sure the full scope of a fire loss is documented and presented to the insurance company.
A Crossroads Community With a Long History
Furlong sits where PA Route 263 meets Edison-Furlong/Forest Grove Road, on the Buckingham–Doylestown line — a crossroads once called Green Tree, then Bushington. That history left a mix of properties, from 19th-century farmhouses to newer builds along Route 263 and Swamp Road. Each raises different coverage questions — building materials, past renovations, code upgrades — even under similar policies. A fire damage adjuster familiar with this range of Furlong properties can look at the full picture, not just what a home is worth on paper.
What a Fire Damage Claim Involves
A fire loss is rarely limited to the room where the fire started. Insurance carriers typically evaluate three distinct categories of damage after a fire, and each can be treated differently under a policy.
Direct Fire Damage
This is the most visible category — charring, structural damage, and the loss of contents in the areas the fire actually reached. It’s usually the most straightforward to document, since the damage is direct and visible, though it can still raise questions about code-upgrade coverage or replacement cost versus actual cash value.
Smoke and Soot Damage to Unaffected Rooms
Smoke travels. Rooms the flames never reached can still end up with soot residue in HVAC systems, drywall, and fabrics, along with a lingering odor that affects livability. This kind of damage is sometimes underestimated in an initial inspection because it isn’t as visually dramatic as fire damage itself — which is why a room-by-room review of the entire property, not just the area of origin, matters.
Water Damage From Firefighting Efforts
Putting out a fire often means water damage to floors, ceilings, and belongings in rooms that never saw flame or smoke. This damage is typically assessed and documented separately, since some policies handle it under different provisions than the fire damage itself.
Documentation That Strengthens a Fire Damage Claim in Furlong
The strength of a fire damage claim often comes down to how well the loss is documented before cleanup or repairs begin. A few pieces of documentation tend to matter most:
- Photos and video of every affected room, taken before cleanup, remediation, or temporary repairs start
- A room-by-room inventory of damaged or destroyed belongings, including approximate age and value where possible
- Contractor and remediation estimates that reflect the full scope of repair — structural work, smoke and soot cleanup, and any water mitigation that was needed
We often see policyholders move quickly to clean up or start repairs, which is understandable, but it can make it harder to account for the full loss afterward. Keeping records of what was removed, replaced, or repaired — including receipts — helps fill in gaps if questions come up later in the process.
When to Bring in a Public Adjuster After a Fire
Not every fire loss requires a public adjuster, but many policyholders find it helpful to bring one in when the damage spans multiple categories — structural, smoke, and water — or when the claim involves additional living expenses, business interruption, or a rebuild. A public adjuster’s role is to review the policy, organize documentation, and communicate with the insurance company on the policyholder’s behalf throughout the process. Some people bring in an adjuster right after the loss, while others reach out after they’ve already started working with their insurer and want a second set of eyes on the claim. Either point can be a reasonable time to ask questions about how a policy applies to a specific loss.
Get Fire Damage Claim Help in Furlong, PA
If your home or business in Furlong has experienced a fire, we’re available to talk through what documentation and next steps look like for your specific situation. Call Alliance Adjustment Group at (267) 880-3000 to reach our team.
435 N Main St, Doylestown, PA 18901. See driving directions.
Serving Furlong and Surrounding Communities
Furlong is home to beautiful neighborhoods, small businesses, and rural properties that deserve strong representation when disaster strikes. Alliance Adjustment Group proudly serves this region and the surrounding towns with dedicated public adjusting support.
Explore our specialized adjuster services in nearby communities:
- Public Adjuster in Doylestown, PA
- Loss Adjuster in Chalfont, PA
- Independent Adjuster in Warrington, PA
- Water Damage Adjuster in Buckingham, PA
- Homeowner Insurance Claim Adjuster in New Britain, PA
Whether your property is just off Forest Grove Road or closer to the New Britain border, our team is ready to help.
Frequently Asked Questions
Does my policy cover temporary housing while my home is being repaired?
Many homeowner policies include additional living expense (ALE) coverage, which can help with temporary housing, meals, and related costs while a home is uninhabitable. Coverage limits and time periods vary by policy, so it’s worth reviewing the specific ALE provisions on your declarations page.
How is smoke damage to rooms the fire didn't reach handled?
These rooms are typically inspected and documented separately from the area of origin, since damage — soot residue, odor, HVAC contamination — can be present even without visible burning. A full walkthrough of the property, not just the room where the fire started, is generally recommended.
What if the fire started from a neighboring property?
Your own homeowner or business policy is usually the first place a claim is filed, regardless of where the fire started. Depending on the circumstances, there may also be options to pursue recovery from the neighboring property’s insurer, which is a separate process from your own claim.
How long does a fire damage claim typically take?
Timelines vary based on the extent of the damage, how quickly documentation is gathered, and how many parties are involved — contractors, remediation companies, mortgage lenders, and others. Larger losses involving structural rebuilding generally take longer than claims limited to smoke or contents damage.
Do I need to make repairs before the claim is settled?
In most cases, repairs beyond emergency mitigation — like boarding up openings or drying out standing water — should wait until the damage has been fully documented. Making repairs too early can make it harder to establish the full scope of the loss.